Don't Jeopardize Your Benefits: Top Mistakes to Avoid When Filing Your Long-Term Disability Claim in the GTA
Life can change in an instant. An unexpected illness or a serious injury can leave you unable to work, facing not only physical and emotional challenges but also significant financial stress. For many hardworking individuals in the Greater Toronto Area (GTA), Long-Term Disability (LTD) benefits are a crucial lifeline, intended to provide income replacement when you need it most.


However, accessing these benefits is often far from straightforward. The application process can be complex, demanding, and confusing. Insurance companies, while providing a valuable service, are also businesses that scrutinize claims closely. Unfortunately, legitimate claims are frequently denied due to errors or omissions made during the application or appeal process.


At Benjamin Law Firm, we've seen firsthand the devastating impact a denied LTD claim can have on individuals and families. As some of the Greater Toronto Area's leading Long-Term Disability Lawyers, we have dedicated our practice to fighting for the rights of the disabled. Our track record speaks for itself: we have helped over 3,500 families navigate the complexities of disability claims and recovered over $60 million in settlements for our clients. We understand the tactics insurers use and, more importantly, we know how to counter them.


Based on our extensive experience, we've identified the most common – and often costly – mistakes people make when filing for LTD benefits. Avoiding these pitfalls can significantly increase your chances of getting your claim approved and securing the financial support you desperately need.


Understanding the Landscape: LTD Insurance

Before diving into the mistakes, it's helpful to understand that LTD insurance policies (whether group policies through your employer or private policies you purchased) are contracts. They contain specific definitions, requirements, and deadlines. The insurer's role is to assess your claim against the terms of that contract. While you see LTD as a safety net, the insurer assesses it based on liability and financial exposure. This inherent tension means you need to present your claim meticulously.


Top 11 Mistakes to Avoid When Filing Your LTD Claim in the GTA:

Making any of these errors can delay your claim, lead to denial, or make an appeal much more difficult.


1. Missing Crucial Deadlines:

  • The Mistake: LTD policies contain strict deadlines for submitting your initial application and for appealing a denial. Failing to submit required forms or appeal documentation within these timeframes can result in your claim being automatically barred, regardless of its merit.
  • Why It Matters: Insurers adhere rigidly to deadlines. Missing one often provides them with an easy, non-medical reason to deny your claim or refuse an appeal.
  • How to Avoid It: Read your policy documents carefully to identify all relevant deadlines. Keep a calendar and set reminders. If facing a denial, contact an experienced LTD lawyer immediately, as appeal deadlines can be very short (sometimes 30-60 days).


2. Submitting Incomplete or Inaccurate Application Forms:

  • The Mistake: Rushing through the application, leaving sections blank, providing vague answers, or unintentionally giving incorrect information (even minor details about job duties or medical history).
  • Why It Matters: Incomplete forms delay processing. Inaccuracies, even honest mistakes, can be used by the insurer to question your credibility later on. Vague descriptions of your symptoms or job duties make it harder for the claims adjudicator to understand the impact of your disability.
  • How to Avoid It: Take your time filling out all forms. Answer every question thoroughly and honestly. Clearly describe your symptoms, limitations, and how they prevent you from performing your job duties. If unsure about a question, seek clarification or legal advice before submitting.


3. Providing Insufficient Medical Evidence:

  • The Mistake: Relying solely on your own description of symptoms without strong, objective medical documentation from treating physicians and specialists. This includes infrequent doctor visits, lack of specialist consultations for specific conditions, or failing to undergo recommended diagnostic testing.
  • Why It Matters: The burden of proof is on you to demonstrate your disability according to the policy's definition. Insurers need objective medical evidence – diagnoses, test results, specialist reports, clinical notes detailing functional limitations – to approve a claim. Subjective complaints alone are rarely enough.
  • How to Avoid It: Maintain regular appointments with your family doctor and any relevant specialists. Ensure your doctors understand the definition of disability in your policy and accurately document your symptoms, diagnosis, prognosis, and specific functional limitations (e.g., inability to sit/stand for prolonged periods, lift certain weights, concentrate, etc.). Request copies of your medical records to ensure they are complete and accurate. Benjamin Law Firm often works directly with treating physicians to ensure the necessary evidence is obtained and presented effectively.


4. Misunderstanding the Definition of "Disability":

  • The Mistake: Not understanding how your policy defines "total disability." Most policies have a two-stage definition:
  • "Own Occupation" Period: Initially (often for the first 24 months), you may be considered disabled if you cannot perform the essential duties of your specific job.
  • "Any Occupation" Period: After that period, the definition often shifts, requiring you to prove you cannot perform any occupation for which you are reasonably suited by education, training, or experience.
  • Why It Matters: Many claims are denied at the "Any Occupation" stage because the claimant doesn't provide sufficient evidence to meet the stricter definition, or they misunderstand what capabilities the insurer believes they still possess.
  • How to Avoid It: Carefully read your policy's definition of disability. Understand when the definition changes. Ensure your medical documentation addresses your inability to perform any suitable work, considering your limitations, skills, and the job market, once you approach the "Any Occupation" transition. Legal counsel is particularly vital at this stage.


5. Not Being Completely Truthful (or Perceived Exaggeration):

  • The Mistake: Intentionally misleading the insurer or exaggerating symptoms out of fear the claim won't be taken seriously. Even minor inconsistencies can be problematic.
  • Why It Matters: Insurers investigate claims thoroughly. If they find evidence contradicting your statements (e.g., through medical records, surveillance, social media), your credibility will be destroyed, and your claim will likely be denied. Fraud is taken very seriously.
  • How to Avoid It: Be honest and consistent in all communications with your doctors and the insurer. Describe your limitations accurately – don't minimize them, but don't exaggerate either. Focus on providing factual information supported by medical evidence.


6. Communicating Poorly or Inappropriately with the Insurer:

  • The Mistake: Agreeing to recorded statements without legal counsel, losing your temper during phone calls, providing rambling or ambiguous answers, or sending emotional emails.
  • Why It Matters: Anything you say to the insurer can be used against you. Recorded statements can capture out-of-context remarks. Emotional outbursts can be noted as non-cooperative behaviour. Ambiguity can be interpreted negatively.
  • How to Avoid It: Keep communication with the insurer professional, factual, and concise. It's often best to communicate in writing (email or registered mail) to maintain a record. Politely decline requests for recorded statements until you have spoken with an LTD lawyer. Let your lawyer handle direct communication whenever possible.


7. Failing to Follow Prescribed Medical Treatment:

  • The Mistake: Not following your doctor's advice, skipping appointments, failing to take prescribed medication, or refusing recommended therapies (like physiotherapy or counselling) without a valid reason documented by your doctor.
  • Why It Matters: Insurers expect you to actively participate in your recovery. Failing to follow reasonable treatment plans can lead them to argue that your disability is prolonged by your own inaction, potentially justifying a denial or termination of benefits.
  • How to Avoid It: Follow your doctor's recommended treatment plan diligently. If you have valid reasons for not pursuing a specific treatment (e.g., side effects, cost, lack of access), discuss this with your doctor and ensure it's documented in your medical file. Keep records of all appointments and treatments attended.


8. Engaging in Activities Inconsistent with Your Reported Limitations (Beware Surveillance!):

  • The Mistake: Performing activities that appear to contradict the physical or mental limitations you've reported to the insurer. This is often captured through surveillance (video) or social media monitoring.
  • Why It Matters: Insurers frequently use surveillance. A video of you carrying groceries, doing yard work, or even appearing happy at a social event can be taken out of context and used to argue you are capable of working, even if these activities cause significant pain or are infrequent. Social media posts (photos, check-ins, comments) can also be misconstrued.
  • How to Avoid It: Be truthful about your limitations, but also be mindful of your actions. Avoid activities that significantly exceed your documented restrictions. Be extremely cautious about what you post on social media – consider setting profiles to private and avoid posting about physical activities or travel. Honesty is key, but so is awareness.


9. Returning to Work Prematurely or Improperly:

  • The Mistake: Feeling pressured by your employer or insurer, or feeling overly optimistic, and attempting to return to work before you are medically ready. Agreeing to unsuitable return-to-work plans without medical clearance.
  • Why It Matters: Returning too soon often leads to re-injury or exacerbation of your condition, potentially resulting in a longer period off work and complications with your LTD claim. If the return is unsuccessful, the insurer may argue you are no longer totally disabled or failed to cooperate.
  • How to Avoid It: Do not attempt to return to work unless you have clear, documented medical approval from your treating physician(s) outlining your capabilities and any necessary accommodations. Review any gradual return-to-work plan carefully with your doctor and your LTD lawyer before agreeing to it.


10. Giving Up After Your Claim is Denied:

  • The Mistake: Assuming a denial is the final word and abandoning the claim without exploring appeal options or seeking legal advice.
  • Why It Matters: Denials are unfortunately common, even for strong claims. Insurers may deny based on insufficient information, differing medical opinions, or misapplication of the policy terms. There are usually internal appeal processes, and importantly, you have the right to take legal action against the insurer. Many denied claims are successfully overturned with legal assistance.
  • How to Avoid It: Don't be discouraged by an initial denial. Carefully review the denial letter to understand the insurer's reasons. Gather any additional supporting evidence. Adhere strictly to appeal deadlines. Most importantly, contact an experienced LTD lawyer like those at Benjamin Law Firm immediately.


11. Not Seeking Legal Advice Early Enough (or At All):

  • The Mistake: Trying to navigate the complex application forms, manage communications with the insurer, understand dense policy language, and handle appeals entirely on your own, only seeking help after encountering major problems or multiple denials.
  • Why It Matters: The LTD claims process is inherently adversarial. The insurer has experienced adjusters and lawyers working for them. Trying to handle it alone puts you at a significant disadvantage. Early legal advice can help you avoid many of the mistakes listed above, ensure your application is strong from the start, and position you for success during appeals if necessary.
  • How to Avoid It: Consult with an experienced LTD lawyer at Benjamin Law Firm as early as possible in the process – ideally before you even submit your application, but certainly as soon as you encounter difficulties or receive a denial.


The Benjamin Law Firm Advantage: Your Advocates in the GTA

Navigating an LTD claim while managing a serious health condition is incredibly challenging. At Benjamin Law Firm, we lift that burden from your shoulders.


  • We Know the System: We deal with insurance companies daily and understand their procedures and tactics.
  • We Build Strong Cases: We work with you and your doctors to gather the crucial medical evidence needed to prove your disability.
  • We Handle Communication: We manage communications with the insurer, protecting you from saying or doing anything that could harm your claim.
  • We Fight Denials: We meticulously review denial letters, craft compelling appeals, and are fully prepared to initiate legal action to secure the benefits you deserve.
  • Proven Success: Our results – over $60 million recovered and more than 3,500 families helped – demonstrate our commitment and effectiveness.


Don't Face the Insurance Company Alone

Your health and financial security are too important to risk by making avoidable mistakes. If you are preparing to file an LTD claim, are currently struggling with the process, or have received a denial letter in the Greater Toronto Area, don't delay.

Contact Benjamin Law Firm today for a confidential consultation. Let our experienced Long-Term Disability lawyers review your situation, explain your rights, and help you avoid the pitfalls that jeopardize so many claims. We are here to fight for you.


Disclaimer: This blog post contains general information only and does not constitute legal advice or create a lawyer-client relationship. Long-Term Disability claims are complex and fact-specific. Laws and insurance policies vary. You should consult with a qualified Long-Term Disability lawyer licensed in your jurisdiction regarding your specific situation. Contact Benjamin Law Firm for personalized legal counsel tailored to your needs in the Greater Toronto Area.
September 17, 2026
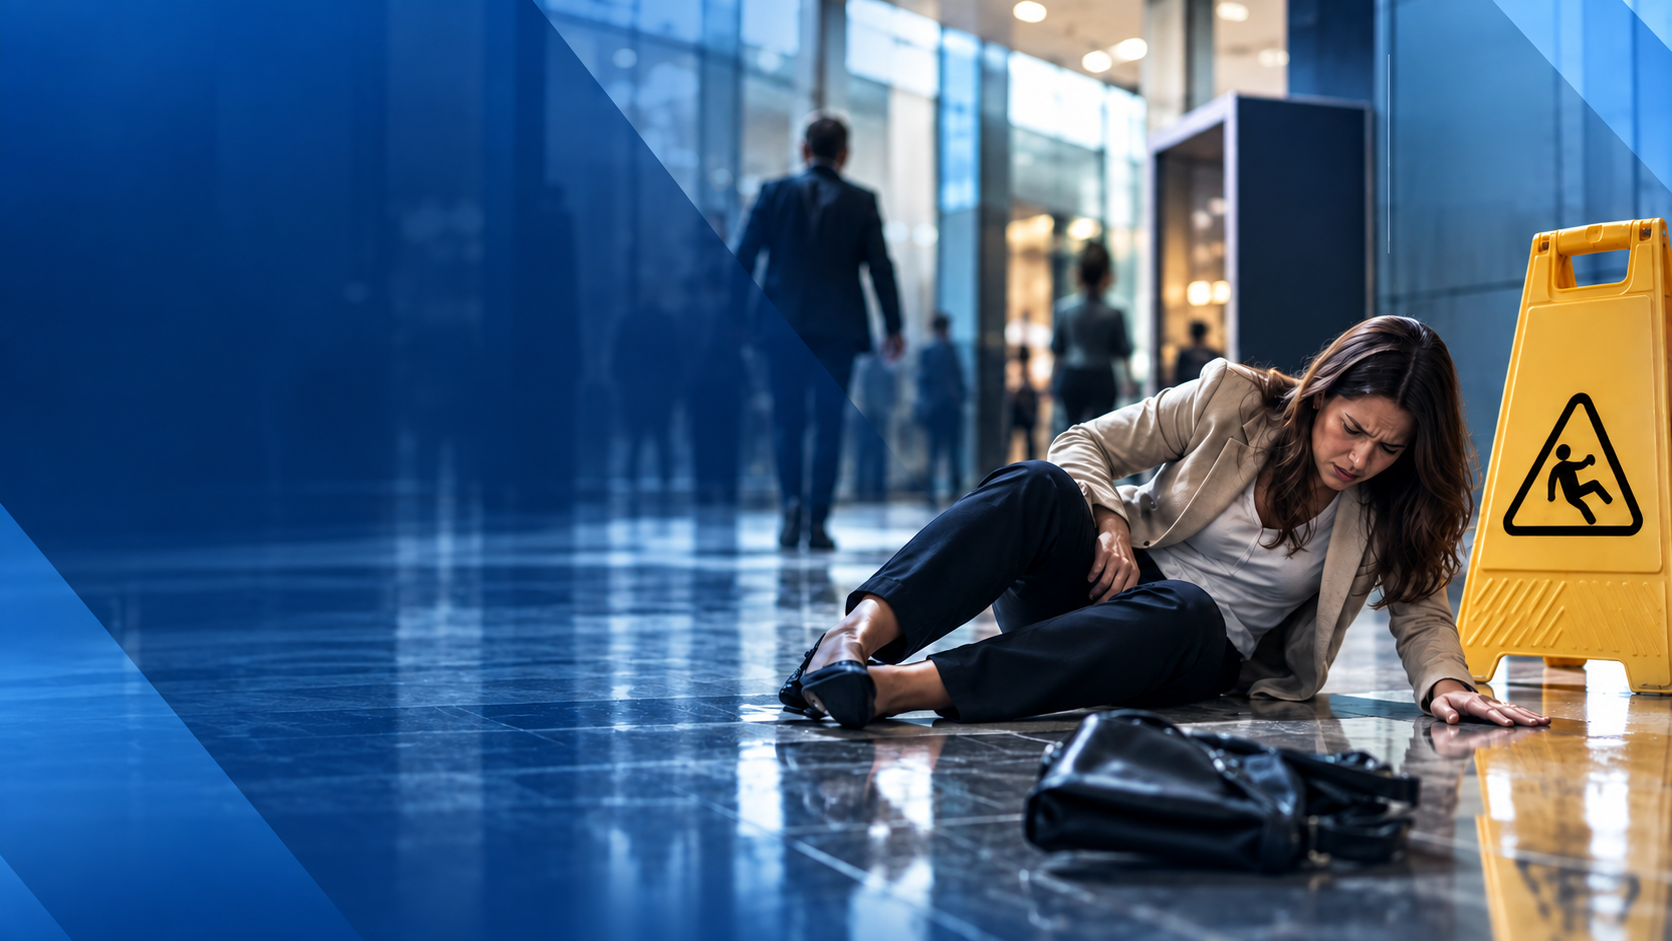
A slip and fall can happen in seconds, but the consequences can last for weeks, months, or even years. If you fall at a grocery store, shopping centre, restaurant, office building, retail store, parking lot, or another commercial property in Ontario, what you do immediately afterward may be important for both your health and your ability to pursue a potential personal injury claim. Commercial property slip and fall cases can involve multiple parties, including property owners, tenants, property managers, maintenance companies, and snow-removal contractors. Evidence can also disappear quickly. A spill may be cleaned, snow may be removed, surveillance footage may be overwritten, and witnesses may become difficult to locate. Knowing what steps to take can help protect you. 1. Get Medical Attention Your health should be the first priority. If you are seriously injured, cannot safely stand, hit your head, experience severe pain, or believe you may have suffered a significant injury, request emergency medical assistance. Even when an injury initially seems minor, consider obtaining medical attention as soon as reasonably possible. Some injuries may not be immediately apparent after a fall. Adrenaline and shock can temporarily mask pain, and symptoms associated with certain soft-tissue injuries or head injuries may develop later. Medical records can also document when symptoms began, what injuries were identified, and what treatment was recommended. Follow your healthcare provider's treatment recommendations and attend scheduled follow-up appointments. 2. Report the Accident Immediately Tell the property owner, manager, security department, store manager, or another appropriate representative that you fell. Ask that an incident report be prepared. Provide accurate information about where and when the accident occurred, but avoid guessing about facts you do not know. If possible, obtain the name and contact information of the person who receives your report. You may also ask for a copy of the incident report or information about how you can obtain one. Reporting the accident promptly creates a record that the incident occurred and alerts the business or property manager to the location of the accident. 3. Photograph and Record the Hazard If you are physically able to do so safely, photograph the area before conditions change. This can be particularly important because the hazard responsible for a fall may disappear shortly afterward. For example, photograph conditions such as: Water or another liquid on a floor Snow or ice Uneven pavement Damaged flooring Broken stairs Loose mats or carpeting Debris in a walkway Poorly maintained entrances Inadequate lighting Missing or damaged handrails Take both close-up and wider photographs. Wider photographs can establish where the hazard was located in relation to entrances, aisles, stairs, parking areas, or other landmarks. If weather contributed to an outdoor accident, photographs showing the general conditions may also be useful. 4. Identify Witnesses If someone saw you fall—or observed the dangerous condition before or after the accident—ask for their name and contact information. Do not assume that the commercial property will collect this information for you. Independent witnesses may later provide valuable information about what happened, what the property looked like, how long a hazard may have existed, or what occurred immediately following your fall. If someone accompanied you, ask them to make their own notes about what they observed while the details are still fresh. 5. Preserve Your Clothing and Footwear Do not immediately throw away the shoes or clothing you were wearing when you fell. Your footwear could become relevant to questions about how the accident occurred. Clothing may also show damage, moisture, dirt, or other evidence associated with the incident. Keep these items in a safe place rather than continuing to use them extensively. 6. Write Down Exactly What Happened Memories fade surprisingly quickly. As soon as you are able, write down everything you remember about the accident. Record the date, approximate time, exact location, weather conditions if relevant, lighting, the condition that caused you to fall, where you landed, who assisted you, witnesses who were present, and any conversations you had with employees or management. Also document your symptoms and how your injuries affect your daily activities afterward. These notes may help you recall important details months later. 7. Be Careful About Statements and Social Media Following an accident, you may be contacted by an insurer, property representative, or another party seeking information. Be accurate, but remember that you may not yet know the full extent of your injuries or all the circumstances surrounding the accident. Consider obtaining legal advice before providing detailed recorded statements or signing documents relating to the incident. You should also think carefully before posting photographs, videos, activity updates, or comments about the accident on social media. Information posted online may potentially become relevant in a personal injury dispute. 8. Ask That Surveillance Footage Be Preserved Many commercial properties use security cameras. Video footage may show the fall itself, the condition of the area before the accident, employees inspecting or cleaning the location, or how long a hazard existed. However, surveillance systems do not necessarily retain footage indefinitely. A lawyer can assess whether steps should be taken to request preservation of relevant surveillance footage and other records, including inspection logs, cleaning records, maintenance reports, and incident documentation. Acting promptly can therefore be important. 9. Understand Ontario's Occupiers' Liability Rules Ontario's Occupiers' Liability Act generally requires an occupier of premises to take reasonable care in the circumstances to see that people entering the premises are reasonably safe. An "occupier" can include a person in physical possession of the premises or someone with responsibility and control over its condition or activities. ( Ontario ) This does not mean that a commercial property owner is automatically liable whenever someone falls. The circumstances surrounding the accident matter. Questions may include what caused the fall, whether the condition presented an unreasonable risk, what inspection or maintenance procedures were in place, and what the parties reasonably did in the circumstances. Determining responsibility can also become complicated when several companies are involved in operating and maintaining a property. 10. Don't Ignore the 60-Day Snow and Ice Notice Requirement This is especially important for Ontario slip and fall claims involving snow or ice. Under Ontario's Occupiers' Liability Act, a person seeking damages for a personal injury caused by snow or ice generally must provide written notice of the claim within 60 days after the injury occurs. The notice must include the date, time, and location of the occurrence and must be personally served or sent by registered mail to an occupier or applicable snow/ice removal contractor. The legislation provides certain exceptions, but you should not assume that an exception will apply. ( Ontario ) This short notice period is one reason it can be important to obtain legal advice quickly after a winter slip and fall. 11. Be Aware of Ontario's Limitation Period Separate from the 60-day snow-and-ice notice requirement, Ontario's Limitations Act, 2002 establishes a basic limitation period that generally prevents a proceeding from being commenced after the second anniversary of the date the claim was discovered. The Act contains specific rules governing when a claim is considered discovered, as well as exceptions and other provisions that can affect limitation periods. ( Ontario ) Because deadlines can depend on the circumstances, waiting until a limitation date approaches can create unnecessary risk. Speak With Benjamin Law About Your Slip and Fall A serious slip and fall can affect your ability to work, care for your family, participate in normal activities, and maintain your independence. You may also face medical, rehabilitation, and other expenses while dealing with pain and limitations caused by your injuries. If you were injured after slipping or falling on commercial property in Ontario, consider obtaining legal advice as soon as possible. Benjamin Law can review the circumstances surrounding the accident, help identify potentially responsible parties, assess applicable deadlines, and explain the legal options that may be available to you. Early action may also provide an opportunity to preserve evidence before conditions change, surveillance footage disappears, or witnesses become difficult to locate. Injured in a slip and fall on commercial property? Contact Benjamin Law to schedule a consultation and learn about your legal options. Benjamin Law Personal Injury Lawyers 🌐 www.benjaminlaw.ca 📞 (416) 736-4994 This article provides general information about Ontario law and is not intended as legal advice. Legal rights and deadlines depend on the circumstances of each case.
August 18, 2026
Nếu quý vị lái xe ở Ontario, tấm hợp đồng bảo hiểm nằm trong ngăn xe của quý vị có thể không bao gồm những gì quý vị nghĩ. Vào ngày 1 tháng 7 năm 2026, Ontario đã chuyển sang hệ thống bảo hiểm xe hơi "tự chọn" (à la carte) mới — một hệ thống cho tài xế nhiều lựa chọn hơn về phí bảo hiểm, nhưng cũng chuyển phần lớn rủi ro tài chính sang cho bất kỳ ai gặp tai nạn xe cộ. Tại Benjamin Law, chúng tôi đã dành hơn 30 năm để giúp người dân Ontario bị thương đấu tranh cho những quyền lợi mà họ xứng đáng được nhận. Cuộc cải cách này là một trong những thay đổi quan trọng nhất ảnh hưởng đến nạn nhân tai nạn trong nhiều năm qua, nhưng hầu hết tài xế đều không biết điều này đã xảy ra. Dưới đây là những gì quý vị cần biết trước khi rơi vào tình huống phải tìm hiểu theo cách khó khăn. Bức Tranh Tổng Quan: Sự Lựa Chọn Đi Kèm Với Rủi Ro Theo hệ thống cũ, một hợp đồng bảo hiểm xe hơi tiêu chuẩn đi kèm với một loạt quyền lợi tai nạn rộng rãi — bồi thường thu nhập, hỗ trợ người chăm sóc, hỗ trợ việc nhà, và nhiều hơn nữa — tất cả đều được bao gồm sẵn. Mô hình "tự chọn" mới tách rời gói quyền lợi này ra. Tài xế giờ đây có thể chọn lựa quyền lợi nào để thêm vào hợp đồng, điều này có thể giúp giảm phí bảo hiểm ban đầu. Nhưng có một điểm mấu chốt: nếu quý vị không chọn tham gia một quyền lợi khi mua hợp đồng, quyền lợi đó sẽ đơn giản là không có nếu quý vị gặp tai nạn — dù quý vị cần đến mức nào. Những Gì Vẫn Bắt Buộc So Với Những Gì Giờ Là Tùy Chọn Chỉ có một loại quyền lợi vẫn bắt buộc trên mọi hợp đồng bảo hiểm xe hơi ở Ontario: chăm sóc y tế, phục hồi chức năng và chăm sóc hỗ trợ (attendant care) . Điều này bao gồm chăm sóc sức khỏe thiết yếu và vật lý trị liệu sau tai nạn, và thực ra có một thay đổi tích cực ở đây (sẽ nói thêm bên dưới). Mọi thứ khác vốn từng đi kèm sẵn giờ đây là tùy chọn thêm. Kể từ ngày 1 tháng 7 năm 2026, các quyền lợi sau đây là tùy chọn — nghĩa là chúng chỉ áp dụng nếu quý vị đã mua riêng: Quyền Lợi Bao Gồm Những Gì Bồi Thường Thu Nhập (IRB) Bù đắp thu nhập bị mất nếu quý vị không thể làm việc do tai nạn Quyền Lợi Người Chăm Sóc Chi trả chi phí thuê người chăm sóc người phụ thuộc trong khi quý vị hồi phục Quyền Lợi Người Không Có Thu Nhập Hỗ trợ tài chính nếu quý vị không có thu nhập nhưng bị tổn thương vĩnh viễn Việc Nhà & Bảo Trì Nhà Cửa Chi trả cho việc thuê người giúp duy trì nhà cửa trong thời gian hồi phục Chi Phí Tang Lễ & Tử Vong Khoản chi trả một lần cho người thân và chi phí mai táng Chăm Sóc Người Phụ Thuộc / Điều Chỉnh Theo Lạm Phát Chi phí giữ trẻ thêm và điều chỉnh quyền lợi hàng năm theo lạm phát Hãy nghĩ về ý nghĩa thực tế của điều này. Nếu quý vị bị thương nặng vào ngày mai và chỉ có mức bảo hiểm tối thiểu bắt buộc, quý vị có thể được điều trị y tế và phục hồi chức năng — nhưng sẽ không có gì để bù đắp thu nhập bị mất, không có gì giúp trả tiền chăm sóc con cái, và không có gì chi trả việc nhà trong khi quý vị đang hồi phục. Ngay cả một chấn thương thảm khốc cũng không còn tự động mở khóa các quyền lợi này nữa. Nếu quý vị không mua bảo hiểm đó, nó sẽ không tồn tại. Một Thay Đổi Thực Sự Có Lợi: Quy Tắc "Người Chi Trả Đầu Tiên" Không phải mọi thứ trong cuộc cải cách này đều bất lợi cho tài xế. Có một thay đổi quan trọng có lợi cho quý vị: kể từ ngày 1 tháng 7 năm 2026, bảo hiểm xe hơi của quý vị giờ đây chi trả trước cho chi phí y tế và phục hồi chức năng sau tai nạn — trước cả bảo hiểm y tế tư nhân hoặc bảo hiểm của nơi làm việc, như Sun Life hay Canada Life. Trước đây, người bị thương phải dùng hết quyền lợi bảo hiểm tư nhân trước khi công ty bảo hiểm xe hơi chi trả bất kỳ khoản nào. Gánh nặng đó giờ đã được đảo ngược, điều này có nghĩa là nhiều nạn nhân tai nạn sẽ được tiếp cận điều trị nhanh hơn. Bảo Hiểm Không Còn Tự Động Đi Theo Quý Vị Có lẽ phần bị bỏ sót nhiều nhất trong cuộc cải cách này là ai thực sự được bảo vệ bởi các quyền lợi tùy chọn. Theo các quy định mới, bảo hiểm tùy chọn được mua sau ngày 1 tháng 7 năm 2026 chỉ áp dụng cho người được bảo hiểm chính, vợ/chồng của họ, những người phụ thuộc được liệt kê, và những tài xế được nêu tên cụ thể trên hợp đồng đó. Điều này có hậu quả thực sự đối với bất kỳ ai không phải là chủ hợp đồng: Người đi bộ và người đi xe đạp bị xe đâm sẽ không tự động nhận được các quyền lợi tùy chọn của tài xế, ngay cả khi tài xế đó đã mua bảo hiểm đầy đủ. Hành khách trong xe của người khác cũng ở trong tình huống tương tự — họ không thừa hưởng quyền lợi tùy chọn của tài xế. Bất kỳ ai lái xe với sự đồng ý của chủ xe , nhưng không được nêu tên trên hợp đồng, cũng bị loại khỏi các quyền lợi tùy chọn. Trong mỗi trường hợp trên, người đó thường phải dựa vào hợp đồng bảo hiểm xe hơi của chính họ — và nếu hợp đồng đó chỉ có mức tối thiểu bắt buộc, họ sẽ chỉ được giới hạn ở quyền lợi y tế và phục hồi chức năng, bất kể tai nạn xảy ra như thế nào hay chấn thương nghiêm trọng ra sao. Tại Sao Điều Này Quan Trọng Đối Với Tài Xế Ontario Đây là thực tế thực tiễn: hai người có thể gặp cùng một loại tai nạn và kết thúc ở những vị trí tài chính rất khác nhau sau đó, hoàn toàn dựa trên việc họ đã chọn những gì khi mua hợp đồng — hoặc liệu họ có đang lái xe của chính mình hay không. Người chỉ có mức tối thiểu bắt buộc, bị thương nặng và không thể làm việc, có thể phải tìm đến bảo hiểm khuyết tật tư nhân (như bảo hiểm khuyết tật ngắn hạn hoặc dài hạn) hoặc các chương trình của chính phủ như trợ cấp ốm đau EI, Ontario Works, ODSP, hoặc CPP Disability chỉ để trang trải cuộc sống. Đây chính là lý do tại sao việc hiểu rõ hợp đồng bảo hiểm của mình trước khi tai nạn xảy ra lại quan trọng đến vậy. Và nếu quý vị đã gặp tai nạn và không chắc mình được hưởng quyền lợi gì, vẫn chưa muộn để tìm hiểu rõ ràng — nhưng quý vị càng sớm biết mình đang đứng ở đâu, quý vị càng có vị thế tốt hơn để bảo vệ quyền lợi của mình. Xin lưu ý rằng những thay đổi này áp dụng cụ thể cho các hợp đồng bảo hiểm xe hơi được mua vào hoặc sau ngày 1 tháng 7 năm 2026. Nếu hợp đồng của quý vị được cấp trước ngày đó, các quy định cũ vẫn tiếp tục được áp dụng. Benjamin Law Có Thể Giúp Gì Cho Quý Vị Chúng tôi áp dụng phương pháp "giáo dục là trên hết", nghĩa là trước khi nói về một vụ khiếu nại, chúng tôi đảm bảo quý vị thực sự hiểu hợp đồng của mình — những gì được bảo hiểm, những gì không, và các lựa chọn của quý vị dựa trên các quy định mới. Dù quý vị đang cố tìm hiểu nên mua bảo hiểm nào, hay đã bị thương và cần biết mình có thể yêu cầu bồi thường gì, đội ngũ của chúng tôi luôn sẵn sàng hướng dẫn quý vị từng bước. Nếu quý vị không chắc chắn hợp đồng bảo hiểm xe hơi của mình thực sự bao gồm những gì, đừng đợi đến sau khi tai nạn xảy ra mới tìm hiểu. Liên hệ Benjamin Law ngay hôm nay để được tư vấn miễn phí: Sandy Chau — 416-830-3653 (Phục vụ 24/7) benjaminlaw.ca Bài viết này chỉ nhằm mục đích cung cấp thông tin chung và không phải là tư vấn pháp lý. Các hợp đồng bảo hiểm khác nhau, và quyền lợi của quý vị phụ thuộc vào phạm vi bảo hiểm cụ thể và hoàn cảnh của quý vị. Vui lòng liên hệ Benjamin Law để được tư vấn về trường hợp của quý vị.
August 18, 2026
If you drive in Ontario, the insurance policy sitting in your glovebox may not cover what you think it does. On July 1, 2026, Ontario moved to a new "à la carte" auto insurance system — one that gives drivers more choice over their premiums, but also shifts significant financial risk onto anyone involved in a motor vehicle accident. At Benjamin Law, we've spent over 30 years helping injured Ontarians fight for the benefits they're owed. This overhaul is one of the most consequential changes to hit accident victims in years, and most drivers have no idea it happened. Here's what you need to know before you're ever in a position to find out the hard way. The Big Picture: Choice Comes With Risk Under the old system, a standard auto policy came bundled with a broad set of accident benefits — income replacement, caregiver support, housekeeping help, and more — all included as a matter of course. The new "à la carte" model breaks that bundle apart. Drivers can now pick and choose which benefits to add to their policy, which can mean lower premiums up front. But there's a catch: if you don't opt into a benefit when you buy your policy, it simply won't be there if you're ever hurt in a crash — no matter how badly you need it. What's Still Mandatory vs. What's Now Optional Only one category of benefit remains mandatory on every Ontario auto policy: medical, rehabilitation, and attendant care . This covers essential healthcare and physical therapy after an accident, and there's actually a positive change here too (more on that below). Everything else that used to come standard is now an add-on. As of July 1, 2026, the following benefits are optional — meaning they only apply if you specifically purchased them: Benefit What It Covers Income Replacement Benefit (IRB) Replaces lost wages if you can't work due to an accident Caregiver Benefits Covers the cost of hiring care for your dependents while you recover Non-Earner Benefits Financial support if you don't earn an income but suffer a permanent impairment Housekeeping & Home Maintenance Pays for help maintaining your home during recovery Death & Funeral Expenses Lump-sum payouts to survivors and burial cost coverage Dependent Care / Indexing Extra childcare costs and annual inflation adjustments to benefits Think about what that means in practice. If you were seriously injured tomorrow and only carried the mandatory minimum, you could receive medical and rehab treatment — but nothing to replace your lost income, nothing to help pay someone to care for your kids, and nothing to cover housekeeping while you're laid up. Even a catastrophic injury doesn't automatically unlock these benefits anymore. If you didn't buy the coverage, it isn't there. A Rule Change That Actually Helps: "First Payer" Not everything about the overhaul cuts against drivers. One important change works in your favour: as of July 1, 2026, your auto insurance now pays first for medical and rehabilitation costs after a crash — ahead of any private or workplace health plan, like Sun Life or Canada Life. Previously, injured people had to exhaust their private benefits before their auto insurer would pay a dollar. That burden has been reversed, which should mean faster access to treatment for many accident victims. Coverage No Longer Follows You Automatically Perhaps the most overlooked part of this overhaul is who the optional benefits actually protect. Under the new rules, optional coverage purchased after July 1, 2026 applies only to the named insured, their spouse, listed dependents, and specifically named drivers on that policy. That has real consequences for anyone who isn't the policyholder: Pedestrians and cyclists struck by a vehicle will not automatically receive the driver's optional benefits, even if that driver purchased robust coverage. Passengers in someone else's vehicle are in the same position — they don't inherit the driver's optional coverage. Anyone driving with the owner's consent , but not named on the policy, is also excluded from optional benefits. In each of these situations, the person generally has to fall back on their own auto insurance policy — and if that policy only carries the mandatory minimum, they're limited to medical and rehab benefits only, regardless of how the accident happened or how serious their injuries are. Why This Matters for Ontario Drivers Here's the practical reality: two people can be involved in the exact same type of accident and end up in very different financial positions afterward, purely based on what boxes they checked when they bought their policy — or whether they were driving their own car at all. Someone with only the mandatory minimum, seriously injured and unable to work, may have to turn to private disability insurance (like short-term or long-term disability coverage) or government programs such as EI sickness benefits, Ontario Works, ODSP, or CPP Disability just to stay afloat. This is precisely why understanding your policy before an accident happens matters so much. And if you've already been in a crash and aren't sure what you're entitled to, it's not too late to get clarity — but the sooner you know where you stand, the better positioned you are to protect your rights. Note that these changes apply specifically to auto insurance policies purchased on or after July 1, 2026. If your policy was issued before that date, the previous rules continue to apply. How Benjamin Law Can Help We take an education-first approach, which means before we talk about a claim, we make sure you actually understand your policy — what's covered, what isn't, and what your options are given the new rules. Whether you're trying to figure out what coverage to buy, or you've already been injured and need to know what you can claim, our team is here to walk you through it step by step. If you're unsure what your auto policy actually covers, don't wait until after an accident to find out. Contact Benjamin Law today for a free consultation: 416-736-4994 | benjaminlaw.ca This article is provided for general informational purposes only and does not constitute legal advice. Insurance policies vary, and your rights depend on your specific coverage and circumstances. Contact Benjamin Law for advice about your situation.

BOOK YOUR FREE CONSULTATION


Fill out the Case Evaluator form below to discuss your case or claim with one of our experienced Family-First legal professionals. At Benjamin Law, we work hard, and fast to get you justice, to solve your problems, and get you the compensation that you deserve.

Contact Us