Standing Your Ground: Why Benjamin Law is the Shield You Need for Your Injury Claim
An injury does more than just cause physical pain; it disrupts the rhythm of your entire life. From the sudden onset of medical bills to the anxiety of missed paychecks, the aftermath of an accident is a high-stress environment where every decision carries significant weight. In the Greater Toronto Area (GTA), navigating the legal landscape of personal injury and long-term disability claims can feel like an uphill battle against a systemic machine designed to minimize your suffering.


At Benjamin Law, we believe that justice shouldn't be reserved for those with the deepest pockets. Founded by Anthony Stephen Benjamin, our firm was built on the principle that every individual deserves high-quality, relentless representation. With over 30 years of experience and more than $60 million recovered for our clients, we have seen how the right legal partner can transform a period of crisis into a journey toward restoration. We are not just a law firm; we are a "family of lawyers" dedicated to protecting your future.


The Reality of the System: Advocacy Born from Experience

The mission of Benjamin Law is rooted in a deep understanding of how the "other side" operates. Before founding the firm, Anthony Stephen Benjamin served with the Financial Services Committee under the Attorney General of Ontario. During his tenure, he witnessed a troubling trend: a systemic gap in how claimants were treated, particularly visual minorities and immigrants.


Data from various legal studies in Ontario suggests that visible minorities often face unique hurdles in the insurance process. For instance, some reports indicate that newcomers or those from diverse backgrounds may be offered lower initial settlements or face more aggressive questioning from adjusters who bank on a lack of familiarity with the Ontario legal system. In Canada, statistics show that members of certain racialized groups, such as Black and South Asian communities, often report higher levels of systemic friction when dealing with large bureaucratic institutions.


Anthony saw this mistreatment firsthand and decided to act. Benjamin Law was founded to serve as a shield for those who might otherwise be intimidated by the daunting litigation process. We understand the nuances of these challenges and provide a supportive, coaching-oriented environment where you are never just a file number.


7 Costly Mistakes That Can Ruin Your Injury Claim

Even the strongest case can be undermined by simple errors made in the days following an accident. At Benjamin Law, we prioritize an "education-first" approach to ensure our clients are empowered to protect their rights. Here are the seven most common pitfalls you must avoid:


1. Delaying Medical Treatment

Ignoring or delaying medical care is the quickest way to sink a claim. Insurance companies are experts at looking for "gaps in treatment." If you wait two weeks to see a doctor, they will argue your injuries weren't serious or were caused by something else entirely. Even if you feel "okay" or just "sore," get a professional medical evaluation immediately to document the baseline of your condition.


2. Not Reporting the Incident Properly

Whether it is a motor vehicle accident, a slip and fall on commercial property, or a workplace injury, there must be a paper trail. Without an official police report or an incident report filed with a property manager, your claim lacks the necessary proof that the event occurred at a specific time and place.


3. Talking to Insurance Companies Without Legal Advice

Insurance adjusters may sound friendly, but their primary goal is to save the company money. They are trained to ask leading questions. A seemingly innocent statement like "I'm doing okay today" can be used as evidence that you are fully recovered. Never provide a recorded statement or discuss the details of your injuries with an adjuster until you have consulted with your legal team at Benjamin Law.


4. Posting on Social Media

In the modern legal world, "anything you say can and will be used against you" extends to your Instagram and Facebook. If you claim to have a debilitating back injury but post a photo of yourself at a family BBQ or a child’s birthday party, insurance investigators will use it to suggest you are exaggerating your pain. When you have an active claim, the best policy is to stay offline.


5. Accepting a Quick Settlement

The "fast money" offered by insurance companies shortly after an accident is almost always a "low-ball" offer. These settlements rarely account for long-term needs, such as future physiotherapy, psychological counseling, or the slow-burning impact of chronic pain on your ability to work. Once you sign a release, you cannot go back for more—even if your condition worsens.


6. Not Keeping Proper Records

Your claim is only as strong as your documentation. We encourage our clients to keep a "recovery diary." Track your medical bills, travel expenses to appointments, missed hours at work, and even daily pain levels. These records provide the concrete evidence needed to secure the compensation you truly deserve.


7. Waiting Too Long to Take Action

In Ontario, the Limitations Act generally provides a two-year window to commence a legal action for personal injury. However, certain notice periods (such as those for municipal slip and falls) can be as short as 10 days. Time is not on your side. Acting early ensures that evidence is preserved and your rights are protected.


The Benjamin Law Difference: Restorative Justice

What truly sets us apart is our commitment to the family unit. We have helped over 3,500 families across the GTA, recognizing that when one person is injured, the entire household feels the strain. Our expertise isn't limited to just injury; we offer a holistic suite of services including Employment Law, Real Estate, and even Caribbean Pension and Labour law, reflecting the diverse needs of the communities we serve.


We take an aggressive stance against insurance companies while maintaining a compassionate hand for our clients. We mitigate the financial and emotional risks of litigation by providing step-by-step guidance, ensuring you understand the trajectory of your case from day one.


Securing Your Future and Your Peace of Mind

An injury claim is about more than just paperwork; it is about your recovery, your financial stability, and your future. The system can be cold and impersonal, but your legal representation shouldn't be. By avoiding the common mistakes mentioned above and partnering with a firm that understands the systemic challenges facing GTA residents, you position yourself for the best possible outcome.


At Benjamin Law, we fight for the underdog. We fight for the families who have been ignored. We fight to ensure that the $60 million we’ve recovered continues to grow, one successful case at a time.


Book Your Consultation Today.


Don’t risk your case by navigating the process alone. Whether you are dealing with a complex personal injury or a denied long-term disability claim, get the guidance, protection, and advocacy you need to win. Let our family protect yours.
September 17, 2026
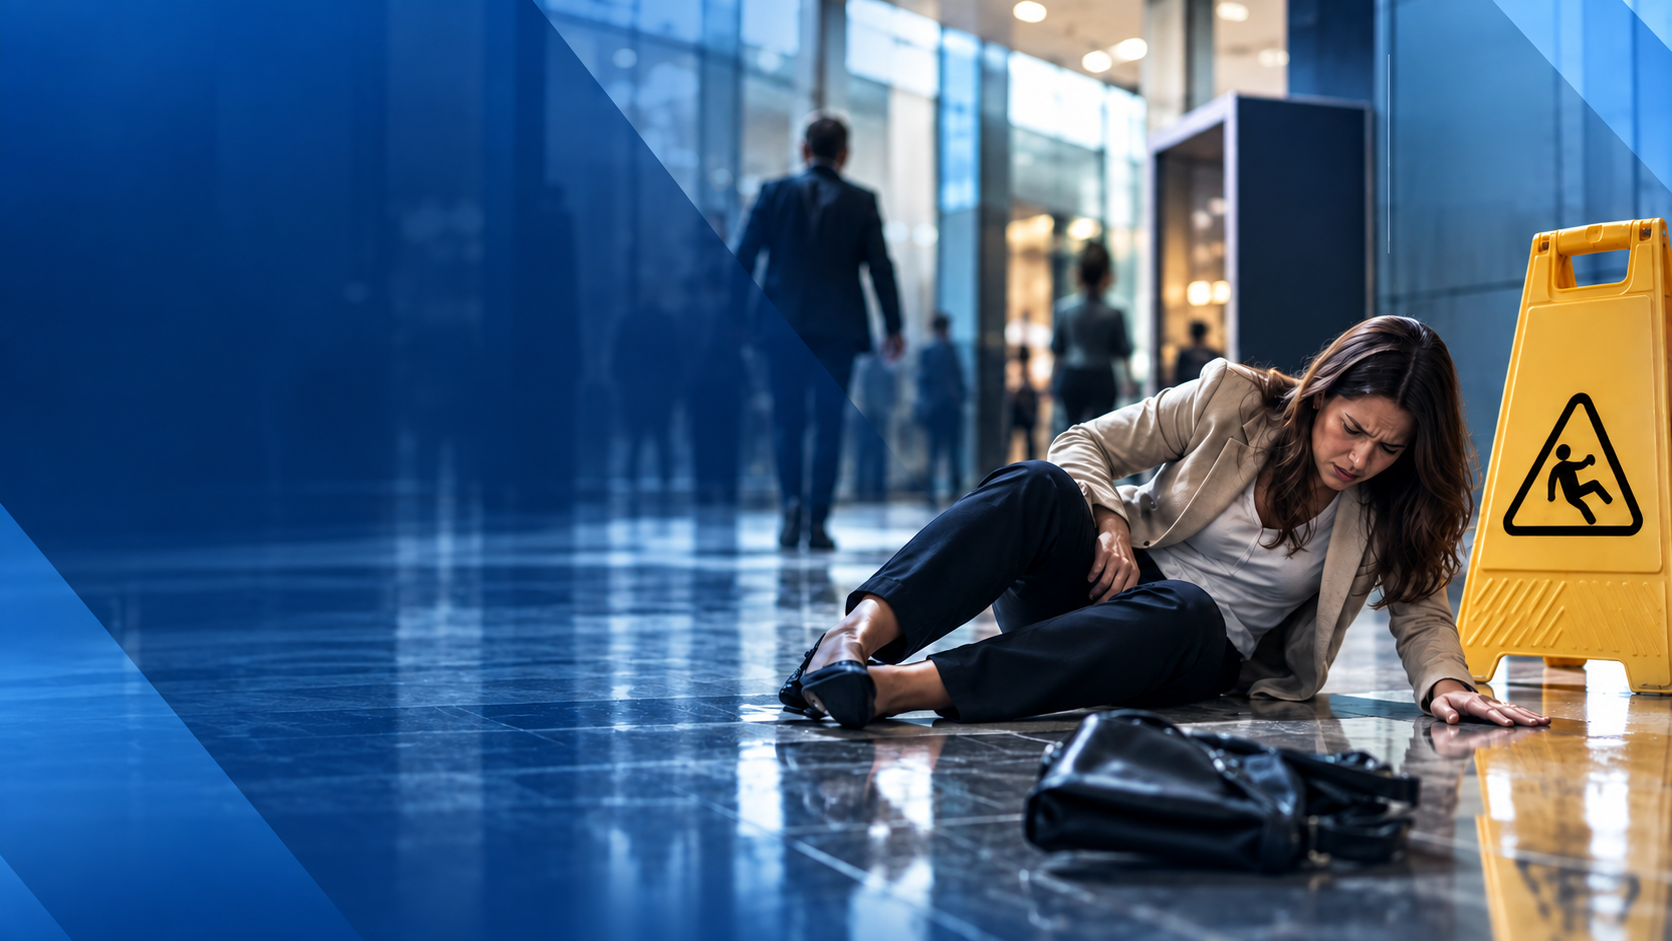
A slip and fall can happen in seconds, but the consequences can last for weeks, months, or even years. If you fall at a grocery store, shopping centre, restaurant, office building, retail store, parking lot, or another commercial property in Ontario, what you do immediately afterward may be important for both your health and your ability to pursue a potential personal injury claim. Commercial property slip and fall cases can involve multiple parties, including property owners, tenants, property managers, maintenance companies, and snow-removal contractors. Evidence can also disappear quickly. A spill may be cleaned, snow may be removed, surveillance footage may be overwritten, and witnesses may become difficult to locate. Knowing what steps to take can help protect you. 1. Get Medical Attention Your health should be the first priority. If you are seriously injured, cannot safely stand, hit your head, experience severe pain, or believe you may have suffered a significant injury, request emergency medical assistance. Even when an injury initially seems minor, consider obtaining medical attention as soon as reasonably possible. Some injuries may not be immediately apparent after a fall. Adrenaline and shock can temporarily mask pain, and symptoms associated with certain soft-tissue injuries or head injuries may develop later. Medical records can also document when symptoms began, what injuries were identified, and what treatment was recommended. Follow your healthcare provider's treatment recommendations and attend scheduled follow-up appointments. 2. Report the Accident Immediately Tell the property owner, manager, security department, store manager, or another appropriate representative that you fell. Ask that an incident report be prepared. Provide accurate information about where and when the accident occurred, but avoid guessing about facts you do not know. If possible, obtain the name and contact information of the person who receives your report. You may also ask for a copy of the incident report or information about how you can obtain one. Reporting the accident promptly creates a record that the incident occurred and alerts the business or property manager to the location of the accident. 3. Photograph and Record the Hazard If you are physically able to do so safely, photograph the area before conditions change. This can be particularly important because the hazard responsible for a fall may disappear shortly afterward. For example, photograph conditions such as: Water or another liquid on a floor Snow or ice Uneven pavement Damaged flooring Broken stairs Loose mats or carpeting Debris in a walkway Poorly maintained entrances Inadequate lighting Missing or damaged handrails Take both close-up and wider photographs. Wider photographs can establish where the hazard was located in relation to entrances, aisles, stairs, parking areas, or other landmarks. If weather contributed to an outdoor accident, photographs showing the general conditions may also be useful. 4. Identify Witnesses If someone saw you fall—or observed the dangerous condition before or after the accident—ask for their name and contact information. Do not assume that the commercial property will collect this information for you. Independent witnesses may later provide valuable information about what happened, what the property looked like, how long a hazard may have existed, or what occurred immediately following your fall. If someone accompanied you, ask them to make their own notes about what they observed while the details are still fresh. 5. Preserve Your Clothing and Footwear Do not immediately throw away the shoes or clothing you were wearing when you fell. Your footwear could become relevant to questions about how the accident occurred. Clothing may also show damage, moisture, dirt, or other evidence associated with the incident. Keep these items in a safe place rather than continuing to use them extensively. 6. Write Down Exactly What Happened Memories fade surprisingly quickly. As soon as you are able, write down everything you remember about the accident. Record the date, approximate time, exact location, weather conditions if relevant, lighting, the condition that caused you to fall, where you landed, who assisted you, witnesses who were present, and any conversations you had with employees or management. Also document your symptoms and how your injuries affect your daily activities afterward. These notes may help you recall important details months later. 7. Be Careful About Statements and Social Media Following an accident, you may be contacted by an insurer, property representative, or another party seeking information. Be accurate, but remember that you may not yet know the full extent of your injuries or all the circumstances surrounding the accident. Consider obtaining legal advice before providing detailed recorded statements or signing documents relating to the incident. You should also think carefully before posting photographs, videos, activity updates, or comments about the accident on social media. Information posted online may potentially become relevant in a personal injury dispute. 8. Ask That Surveillance Footage Be Preserved Many commercial properties use security cameras. Video footage may show the fall itself, the condition of the area before the accident, employees inspecting or cleaning the location, or how long a hazard existed. However, surveillance systems do not necessarily retain footage indefinitely. A lawyer can assess whether steps should be taken to request preservation of relevant surveillance footage and other records, including inspection logs, cleaning records, maintenance reports, and incident documentation. Acting promptly can therefore be important. 9. Understand Ontario's Occupiers' Liability Rules Ontario's Occupiers' Liability Act generally requires an occupier of premises to take reasonable care in the circumstances to see that people entering the premises are reasonably safe. An "occupier" can include a person in physical possession of the premises or someone with responsibility and control over its condition or activities. ( Ontario ) This does not mean that a commercial property owner is automatically liable whenever someone falls. The circumstances surrounding the accident matter. Questions may include what caused the fall, whether the condition presented an unreasonable risk, what inspection or maintenance procedures were in place, and what the parties reasonably did in the circumstances. Determining responsibility can also become complicated when several companies are involved in operating and maintaining a property. 10. Don't Ignore the 60-Day Snow and Ice Notice Requirement This is especially important for Ontario slip and fall claims involving snow or ice. Under Ontario's Occupiers' Liability Act, a person seeking damages for a personal injury caused by snow or ice generally must provide written notice of the claim within 60 days after the injury occurs. The notice must include the date, time, and location of the occurrence and must be personally served or sent by registered mail to an occupier or applicable snow/ice removal contractor. The legislation provides certain exceptions, but you should not assume that an exception will apply. ( Ontario ) This short notice period is one reason it can be important to obtain legal advice quickly after a winter slip and fall. 11. Be Aware of Ontario's Limitation Period Separate from the 60-day snow-and-ice notice requirement, Ontario's Limitations Act, 2002 establishes a basic limitation period that generally prevents a proceeding from being commenced after the second anniversary of the date the claim was discovered. The Act contains specific rules governing when a claim is considered discovered, as well as exceptions and other provisions that can affect limitation periods. ( Ontario ) Because deadlines can depend on the circumstances, waiting until a limitation date approaches can create unnecessary risk. Speak With Benjamin Law About Your Slip and Fall A serious slip and fall can affect your ability to work, care for your family, participate in normal activities, and maintain your independence. You may also face medical, rehabilitation, and other expenses while dealing with pain and limitations caused by your injuries. If you were injured after slipping or falling on commercial property in Ontario, consider obtaining legal advice as soon as possible. Benjamin Law can review the circumstances surrounding the accident, help identify potentially responsible parties, assess applicable deadlines, and explain the legal options that may be available to you. Early action may also provide an opportunity to preserve evidence before conditions change, surveillance footage disappears, or witnesses become difficult to locate. Injured in a slip and fall on commercial property? Contact Benjamin Law to schedule a consultation and learn about your legal options. Benjamin Law Personal Injury Lawyers 🌐 www.benjaminlaw.ca 📞 (416) 736-4994 This article provides general information about Ontario law and is not intended as legal advice. Legal rights and deadlines depend on the circumstances of each case.
August 18, 2026
Nếu quý vị lái xe ở Ontario, tấm hợp đồng bảo hiểm nằm trong ngăn xe của quý vị có thể không bao gồm những gì quý vị nghĩ. Vào ngày 1 tháng 7 năm 2026, Ontario đã chuyển sang hệ thống bảo hiểm xe hơi "tự chọn" (à la carte) mới — một hệ thống cho tài xế nhiều lựa chọn hơn về phí bảo hiểm, nhưng cũng chuyển phần lớn rủi ro tài chính sang cho bất kỳ ai gặp tai nạn xe cộ. Tại Benjamin Law, chúng tôi đã dành hơn 30 năm để giúp người dân Ontario bị thương đấu tranh cho những quyền lợi mà họ xứng đáng được nhận. Cuộc cải cách này là một trong những thay đổi quan trọng nhất ảnh hưởng đến nạn nhân tai nạn trong nhiều năm qua, nhưng hầu hết tài xế đều không biết điều này đã xảy ra. Dưới đây là những gì quý vị cần biết trước khi rơi vào tình huống phải tìm hiểu theo cách khó khăn. Bức Tranh Tổng Quan: Sự Lựa Chọn Đi Kèm Với Rủi Ro Theo hệ thống cũ, một hợp đồng bảo hiểm xe hơi tiêu chuẩn đi kèm với một loạt quyền lợi tai nạn rộng rãi — bồi thường thu nhập, hỗ trợ người chăm sóc, hỗ trợ việc nhà, và nhiều hơn nữa — tất cả đều được bao gồm sẵn. Mô hình "tự chọn" mới tách rời gói quyền lợi này ra. Tài xế giờ đây có thể chọn lựa quyền lợi nào để thêm vào hợp đồng, điều này có thể giúp giảm phí bảo hiểm ban đầu. Nhưng có một điểm mấu chốt: nếu quý vị không chọn tham gia một quyền lợi khi mua hợp đồng, quyền lợi đó sẽ đơn giản là không có nếu quý vị gặp tai nạn — dù quý vị cần đến mức nào. Những Gì Vẫn Bắt Buộc So Với Những Gì Giờ Là Tùy Chọn Chỉ có một loại quyền lợi vẫn bắt buộc trên mọi hợp đồng bảo hiểm xe hơi ở Ontario: chăm sóc y tế, phục hồi chức năng và chăm sóc hỗ trợ (attendant care) . Điều này bao gồm chăm sóc sức khỏe thiết yếu và vật lý trị liệu sau tai nạn, và thực ra có một thay đổi tích cực ở đây (sẽ nói thêm bên dưới). Mọi thứ khác vốn từng đi kèm sẵn giờ đây là tùy chọn thêm. Kể từ ngày 1 tháng 7 năm 2026, các quyền lợi sau đây là tùy chọn — nghĩa là chúng chỉ áp dụng nếu quý vị đã mua riêng: Quyền Lợi Bao Gồm Những Gì Bồi Thường Thu Nhập (IRB) Bù đắp thu nhập bị mất nếu quý vị không thể làm việc do tai nạn Quyền Lợi Người Chăm Sóc Chi trả chi phí thuê người chăm sóc người phụ thuộc trong khi quý vị hồi phục Quyền Lợi Người Không Có Thu Nhập Hỗ trợ tài chính nếu quý vị không có thu nhập nhưng bị tổn thương vĩnh viễn Việc Nhà & Bảo Trì Nhà Cửa Chi trả cho việc thuê người giúp duy trì nhà cửa trong thời gian hồi phục Chi Phí Tang Lễ & Tử Vong Khoản chi trả một lần cho người thân và chi phí mai táng Chăm Sóc Người Phụ Thuộc / Điều Chỉnh Theo Lạm Phát Chi phí giữ trẻ thêm và điều chỉnh quyền lợi hàng năm theo lạm phát Hãy nghĩ về ý nghĩa thực tế của điều này. Nếu quý vị bị thương nặng vào ngày mai và chỉ có mức bảo hiểm tối thiểu bắt buộc, quý vị có thể được điều trị y tế và phục hồi chức năng — nhưng sẽ không có gì để bù đắp thu nhập bị mất, không có gì giúp trả tiền chăm sóc con cái, và không có gì chi trả việc nhà trong khi quý vị đang hồi phục. Ngay cả một chấn thương thảm khốc cũng không còn tự động mở khóa các quyền lợi này nữa. Nếu quý vị không mua bảo hiểm đó, nó sẽ không tồn tại. Một Thay Đổi Thực Sự Có Lợi: Quy Tắc "Người Chi Trả Đầu Tiên" Không phải mọi thứ trong cuộc cải cách này đều bất lợi cho tài xế. Có một thay đổi quan trọng có lợi cho quý vị: kể từ ngày 1 tháng 7 năm 2026, bảo hiểm xe hơi của quý vị giờ đây chi trả trước cho chi phí y tế và phục hồi chức năng sau tai nạn — trước cả bảo hiểm y tế tư nhân hoặc bảo hiểm của nơi làm việc, như Sun Life hay Canada Life. Trước đây, người bị thương phải dùng hết quyền lợi bảo hiểm tư nhân trước khi công ty bảo hiểm xe hơi chi trả bất kỳ khoản nào. Gánh nặng đó giờ đã được đảo ngược, điều này có nghĩa là nhiều nạn nhân tai nạn sẽ được tiếp cận điều trị nhanh hơn. Bảo Hiểm Không Còn Tự Động Đi Theo Quý Vị Có lẽ phần bị bỏ sót nhiều nhất trong cuộc cải cách này là ai thực sự được bảo vệ bởi các quyền lợi tùy chọn. Theo các quy định mới, bảo hiểm tùy chọn được mua sau ngày 1 tháng 7 năm 2026 chỉ áp dụng cho người được bảo hiểm chính, vợ/chồng của họ, những người phụ thuộc được liệt kê, và những tài xế được nêu tên cụ thể trên hợp đồng đó. Điều này có hậu quả thực sự đối với bất kỳ ai không phải là chủ hợp đồng: Người đi bộ và người đi xe đạp bị xe đâm sẽ không tự động nhận được các quyền lợi tùy chọn của tài xế, ngay cả khi tài xế đó đã mua bảo hiểm đầy đủ. Hành khách trong xe của người khác cũng ở trong tình huống tương tự — họ không thừa hưởng quyền lợi tùy chọn của tài xế. Bất kỳ ai lái xe với sự đồng ý của chủ xe , nhưng không được nêu tên trên hợp đồng, cũng bị loại khỏi các quyền lợi tùy chọn. Trong mỗi trường hợp trên, người đó thường phải dựa vào hợp đồng bảo hiểm xe hơi của chính họ — và nếu hợp đồng đó chỉ có mức tối thiểu bắt buộc, họ sẽ chỉ được giới hạn ở quyền lợi y tế và phục hồi chức năng, bất kể tai nạn xảy ra như thế nào hay chấn thương nghiêm trọng ra sao. Tại Sao Điều Này Quan Trọng Đối Với Tài Xế Ontario Đây là thực tế thực tiễn: hai người có thể gặp cùng một loại tai nạn và kết thúc ở những vị trí tài chính rất khác nhau sau đó, hoàn toàn dựa trên việc họ đã chọn những gì khi mua hợp đồng — hoặc liệu họ có đang lái xe của chính mình hay không. Người chỉ có mức tối thiểu bắt buộc, bị thương nặng và không thể làm việc, có thể phải tìm đến bảo hiểm khuyết tật tư nhân (như bảo hiểm khuyết tật ngắn hạn hoặc dài hạn) hoặc các chương trình của chính phủ như trợ cấp ốm đau EI, Ontario Works, ODSP, hoặc CPP Disability chỉ để trang trải cuộc sống. Đây chính là lý do tại sao việc hiểu rõ hợp đồng bảo hiểm của mình trước khi tai nạn xảy ra lại quan trọng đến vậy. Và nếu quý vị đã gặp tai nạn và không chắc mình được hưởng quyền lợi gì, vẫn chưa muộn để tìm hiểu rõ ràng — nhưng quý vị càng sớm biết mình đang đứng ở đâu, quý vị càng có vị thế tốt hơn để bảo vệ quyền lợi của mình. Xin lưu ý rằng những thay đổi này áp dụng cụ thể cho các hợp đồng bảo hiểm xe hơi được mua vào hoặc sau ngày 1 tháng 7 năm 2026. Nếu hợp đồng của quý vị được cấp trước ngày đó, các quy định cũ vẫn tiếp tục được áp dụng. Benjamin Law Có Thể Giúp Gì Cho Quý Vị Chúng tôi áp dụng phương pháp "giáo dục là trên hết", nghĩa là trước khi nói về một vụ khiếu nại, chúng tôi đảm bảo quý vị thực sự hiểu hợp đồng của mình — những gì được bảo hiểm, những gì không, và các lựa chọn của quý vị dựa trên các quy định mới. Dù quý vị đang cố tìm hiểu nên mua bảo hiểm nào, hay đã bị thương và cần biết mình có thể yêu cầu bồi thường gì, đội ngũ của chúng tôi luôn sẵn sàng hướng dẫn quý vị từng bước. Nếu quý vị không chắc chắn hợp đồng bảo hiểm xe hơi của mình thực sự bao gồm những gì, đừng đợi đến sau khi tai nạn xảy ra mới tìm hiểu. Liên hệ Benjamin Law ngay hôm nay để được tư vấn miễn phí: Sandy Chau — 416-830-3653 (Phục vụ 24/7) benjaminlaw.ca Bài viết này chỉ nhằm mục đích cung cấp thông tin chung và không phải là tư vấn pháp lý. Các hợp đồng bảo hiểm khác nhau, và quyền lợi của quý vị phụ thuộc vào phạm vi bảo hiểm cụ thể và hoàn cảnh của quý vị. Vui lòng liên hệ Benjamin Law để được tư vấn về trường hợp của quý vị.
August 18, 2026
If you drive in Ontario, the insurance policy sitting in your glovebox may not cover what you think it does. On July 1, 2026, Ontario moved to a new "à la carte" auto insurance system — one that gives drivers more choice over their premiums, but also shifts significant financial risk onto anyone involved in a motor vehicle accident. At Benjamin Law, we've spent over 30 years helping injured Ontarians fight for the benefits they're owed. This overhaul is one of the most consequential changes to hit accident victims in years, and most drivers have no idea it happened. Here's what you need to know before you're ever in a position to find out the hard way. The Big Picture: Choice Comes With Risk Under the old system, a standard auto policy came bundled with a broad set of accident benefits — income replacement, caregiver support, housekeeping help, and more — all included as a matter of course. The new "à la carte" model breaks that bundle apart. Drivers can now pick and choose which benefits to add to their policy, which can mean lower premiums up front. But there's a catch: if you don't opt into a benefit when you buy your policy, it simply won't be there if you're ever hurt in a crash — no matter how badly you need it. What's Still Mandatory vs. What's Now Optional Only one category of benefit remains mandatory on every Ontario auto policy: medical, rehabilitation, and attendant care . This covers essential healthcare and physical therapy after an accident, and there's actually a positive change here too (more on that below). Everything else that used to come standard is now an add-on. As of July 1, 2026, the following benefits are optional — meaning they only apply if you specifically purchased them: Benefit What It Covers Income Replacement Benefit (IRB) Replaces lost wages if you can't work due to an accident Caregiver Benefits Covers the cost of hiring care for your dependents while you recover Non-Earner Benefits Financial support if you don't earn an income but suffer a permanent impairment Housekeeping & Home Maintenance Pays for help maintaining your home during recovery Death & Funeral Expenses Lump-sum payouts to survivors and burial cost coverage Dependent Care / Indexing Extra childcare costs and annual inflation adjustments to benefits Think about what that means in practice. If you were seriously injured tomorrow and only carried the mandatory minimum, you could receive medical and rehab treatment — but nothing to replace your lost income, nothing to help pay someone to care for your kids, and nothing to cover housekeeping while you're laid up. Even a catastrophic injury doesn't automatically unlock these benefits anymore. If you didn't buy the coverage, it isn't there. A Rule Change That Actually Helps: "First Payer" Not everything about the overhaul cuts against drivers. One important change works in your favour: as of July 1, 2026, your auto insurance now pays first for medical and rehabilitation costs after a crash — ahead of any private or workplace health plan, like Sun Life or Canada Life. Previously, injured people had to exhaust their private benefits before their auto insurer would pay a dollar. That burden has been reversed, which should mean faster access to treatment for many accident victims. Coverage No Longer Follows You Automatically Perhaps the most overlooked part of this overhaul is who the optional benefits actually protect. Under the new rules, optional coverage purchased after July 1, 2026 applies only to the named insured, their spouse, listed dependents, and specifically named drivers on that policy. That has real consequences for anyone who isn't the policyholder: Pedestrians and cyclists struck by a vehicle will not automatically receive the driver's optional benefits, even if that driver purchased robust coverage. Passengers in someone else's vehicle are in the same position — they don't inherit the driver's optional coverage. Anyone driving with the owner's consent , but not named on the policy, is also excluded from optional benefits. In each of these situations, the person generally has to fall back on their own auto insurance policy — and if that policy only carries the mandatory minimum, they're limited to medical and rehab benefits only, regardless of how the accident happened or how serious their injuries are. Why This Matters for Ontario Drivers Here's the practical reality: two people can be involved in the exact same type of accident and end up in very different financial positions afterward, purely based on what boxes they checked when they bought their policy — or whether they were driving their own car at all. Someone with only the mandatory minimum, seriously injured and unable to work, may have to turn to private disability insurance (like short-term or long-term disability coverage) or government programs such as EI sickness benefits, Ontario Works, ODSP, or CPP Disability just to stay afloat. This is precisely why understanding your policy before an accident happens matters so much. And if you've already been in a crash and aren't sure what you're entitled to, it's not too late to get clarity — but the sooner you know where you stand, the better positioned you are to protect your rights. Note that these changes apply specifically to auto insurance policies purchased on or after July 1, 2026. If your policy was issued before that date, the previous rules continue to apply. How Benjamin Law Can Help We take an education-first approach, which means before we talk about a claim, we make sure you actually understand your policy — what's covered, what isn't, and what your options are given the new rules. Whether you're trying to figure out what coverage to buy, or you've already been injured and need to know what you can claim, our team is here to walk you through it step by step. If you're unsure what your auto policy actually covers, don't wait until after an accident to find out. Contact Benjamin Law today for a free consultation: 416-736-4994 | benjaminlaw.ca This article is provided for general informational purposes only and does not constitute legal advice. Insurance policies vary, and your rights depend on your specific coverage and circumstances. Contact Benjamin Law for advice about your situation.

BOOK YOUR FREE CONSULTATION


Fill out the Case Evaluator form below to discuss your case or claim with one of our experienced Family-First legal professionals. At Benjamin Law, we work hard, and fast to get you justice, to solve your problems, and get you the compensation that you deserve.

Contact Us